

Strong revenue growth does not prove competitive strength. A company can report impressive results while losing ground to faster, better-capitalised rivals, simply because its market is expanding. Competitor benchmarking in due diligence exists to separate the two. It measures the target against the real performance standards of its market, so that the buyer can see whether the business leads, keeps pace or is carried by conditions that will not last. Within Commercial Due Diligence, benchmarking is the discipline that replaces management’s narrative with market-relative evidence: share, growth, pricing power, margins, innovation, efficiency and strategic position, each compared with the companies that actually compete for the same customers. The conclusions feed directly into valuation, deal structure and the integration plan. A business is not strong because it is growing. It is strong because it is growing faster and more profitably than those it competes with.
What Is Competitor Benchmarking in Due Diligence?
Competitor benchmarking is the structured comparison of a target company’s commercial, operational and financial performance with that of its most relevant competitors. It forms part of commercial due diligence and answers a specific question: does the target’s performance reflect a durable competitive advantage, or does it reflect temporary market conditions that competitors are exploiting equally well or better?
The exercise is decisive for three reasons. It tests whether the growth and margin assumptions in the business plan are achievable against competitive pressure. It identifies where the target is exposed to erosion of share or price. And it shows the buyer what must change after closing for the investment thesis to hold.
Identifying the True Competitive Set
Benchmarking is only as reliable as the peer group. Management presentations often compare the target with weaker or less relevant companies. The diligence team must build the competitive set independently, starting from the customer’s choices rather than the target’s preferences.
| Competitor Type | Definition | What to Benchmark | Why It Matters |
|---|---|---|---|
| Direct competitors | Comparable products or services sold to the same customer segments | Share, pricing, margins, win rates, customer retention | Defines the immediate contest for revenue and price |
| Indirect competitors | Alternative products or business models meeting the same need | Substitution trends, relative cost to the customer | Reveals demand that can disappear without a direct rival winning it |
| Emerging disruptors | New entrants with different pricing, technology or distribution models | Growth rate, funding, customer acquisition approach | Shows how the competitive set may look by the end of the holding period |
Only once the full set is mapped can comparisons be made with confidence. A target that leads its chosen peers but trails the companies customers actually consider is not a leader.
How Should Market Share Be Benchmarked?
Market share is the most direct measure of competitive standing, but it must be read in three ways. Absolute share is the target’s proportion of total market revenue. It establishes a baseline but can conceal a weak position in a fragmented market. Relative share compares the target with the largest competitor. A business with ten per cent of the market may look substantial until it becomes clear that the leader holds forty per cent and sets industry prices. Segment-level share shows whether the target leads in high-value, growing niches or depends on declining ones.
The trend matters as much as the level. A stable share in a growing market means the target is keeping pace. A falling share in a growing market means it is losing ground, even if its revenue is rising.
Share should also be tested at customer level. Retention rates, wallet share within key accounts and win-loss records against named competitors show whether share is being defended in the accounts that matter most or replaced by smaller, less profitable customers.
Growth: Expansion or Market Tide?
Revenue growth must be compared against three benchmarks. The first is the growth rate of the market itself. Growth below the market rate signals declining share. The second is the growth of direct peers operating under the same conditions. If competitors with similar resources grow faster, the target’s model needs scrutiny. The third is growth by segment. Strong growth concentrated in declining segments often signals a temporary spike rather than durable expansion.
Pricing Power and Margin Benchmarking
Competitive strength shows most clearly in pricing and margins. Gross margin comparisons reveal whether the target commands a premium relative to its cost of delivery. Operating margin comparisons show whether its cost structure is efficient relative to peers. Price sensitivity analysis, drawn from customer interviews, discount data and win-loss records, shows whether customers accept price increases or whether volume depends on discounting.
A target that grows faster than peers while earning lower margins may be buying growth with price. That pattern can reverse quickly when competitors respond or when the buyer tries to restore margins after closing.
Innovation, Efficiency and Strategic Position
Three further dimensions complete the comparison. Product and innovation benchmarking compares the breadth and quality of the portfolio, research and development investment and the speed of product releases. Lower investment than peers may support current margins while weakening future relevance.
Operational efficiency benchmarking compares cost structure, revenue per sales employee, customer acquisition cost and service cost. Structural cost disadvantages create long-term margin pressure that no commercial strategy can fully offset.
Strategic position benchmarking assesses brand strength, distribution reach, partnerships, technology capability and regulatory position. Companies that hold these structural advantages tend to direct the market. Those that lack them remain exposed even when current results look strong.
A Worked Example: Reading the Benchmarks Together
Consider an illustrative target in a market growing at eight per cent a year. Management presents twelve per cent revenue growth as evidence of leadership. The diligence team benchmarks the target against the two most relevant direct competitors.
| Metric | Target | Competitor A | Competitor B | Reading |
|---|---|---|---|---|
| Revenue growth | 12% | 18% | 9% | Gaining on the market, losing to the leader |
| Relative market share | 0.45 | 1.00 | 0.60 | Third in the market |
| Gross margin | 34% | 41% | 38% | Lowest pricing power |
| Average discount to list price | 17% | 8% | 11% | Growth supported by discounting |
| R&D as share of revenue | 3% | 7% | 5% | Underinvesting in product |
Read together, the metrics change the story. The target is growing faster than the market, but it is growing more slowly than the leader, earning the lowest gross margin and offering the deepest discounts. Its margins are partly supported by low research spending. The growth is real but bought: the target is gaining share from weaker competitors through price while the leader extends its lead through product. A buyer relying on management’s plan would assume continued growth with improving margins. The benchmarks suggest that restoring margins would slow growth and that closing the product gap will require investment. Those findings belong in the valuation, the deal terms and the first-year plan. The figures are illustrative. The method of reading them together is not.
How Do Benchmarking Findings Change the Deal?
Benchmarking is not an academic exercise. Its conclusions should move four parts of the transaction. The first is valuation. Where benchmarks show that growth depends on discounting or underinvestment, the forecast should be rebuilt with realistic margins and the investment needed to close the gap, and the price adjusted accordingly. The second is deal structure. Where the outcome depends on whether the target can sustain its position, part of the consideration can be deferred or linked to performance through an earn-out, so that the seller shares the risk the benchmarks have identified.
The third is the integration plan. Benchmarks show where the target trails its peers and therefore where the buyer must act first: pricing discipline, product investment, sales productivity or cost structure. The fourth is the decision itself. Where the benchmarks show a structural disadvantage that the buyer cannot realistically correct, the right outcome may be to stop. Capital deployed into a business that is losing its competitive contest rarely produces the returns the model assumes. Benchmarking that does not change a number has not done its job.
Benchmarking in the UAE and the Wider Gulf
Benchmarking in the UAE presents particular data challenges. Many competitors are privately held and do not publish detailed financial statements, and market data for specialised segments may be limited. Diligence teams typically combine the limited public information available, including disclosures by companies listed on the Abu Dhabi Securities Exchange and the Dubai Financial Market, with customer and channel interviews, pricing studies, trade data and expert input. The resulting estimates should be presented as ranges with their sources stated, not as precise figures.
Competition law also shapes the exercise. Where the buyer is itself a competitor of the target, the exchange of competitively sensitive information during diligence, such as current pricing, margins by customer or strategic plans, should be confined to clean team arrangements. In addition, the market share analysis prepared for benchmarking may be relevant to whether the transaction requires notification under the UAE Competition Law, Federal Decree-Law No. 36 of 2023, whose merger control regime applies turnover and market share thresholds set by implementing decisions. The commercial and regulatory analyses should be prepared consistently.
Original Analysis: The Relative Strength Wheel
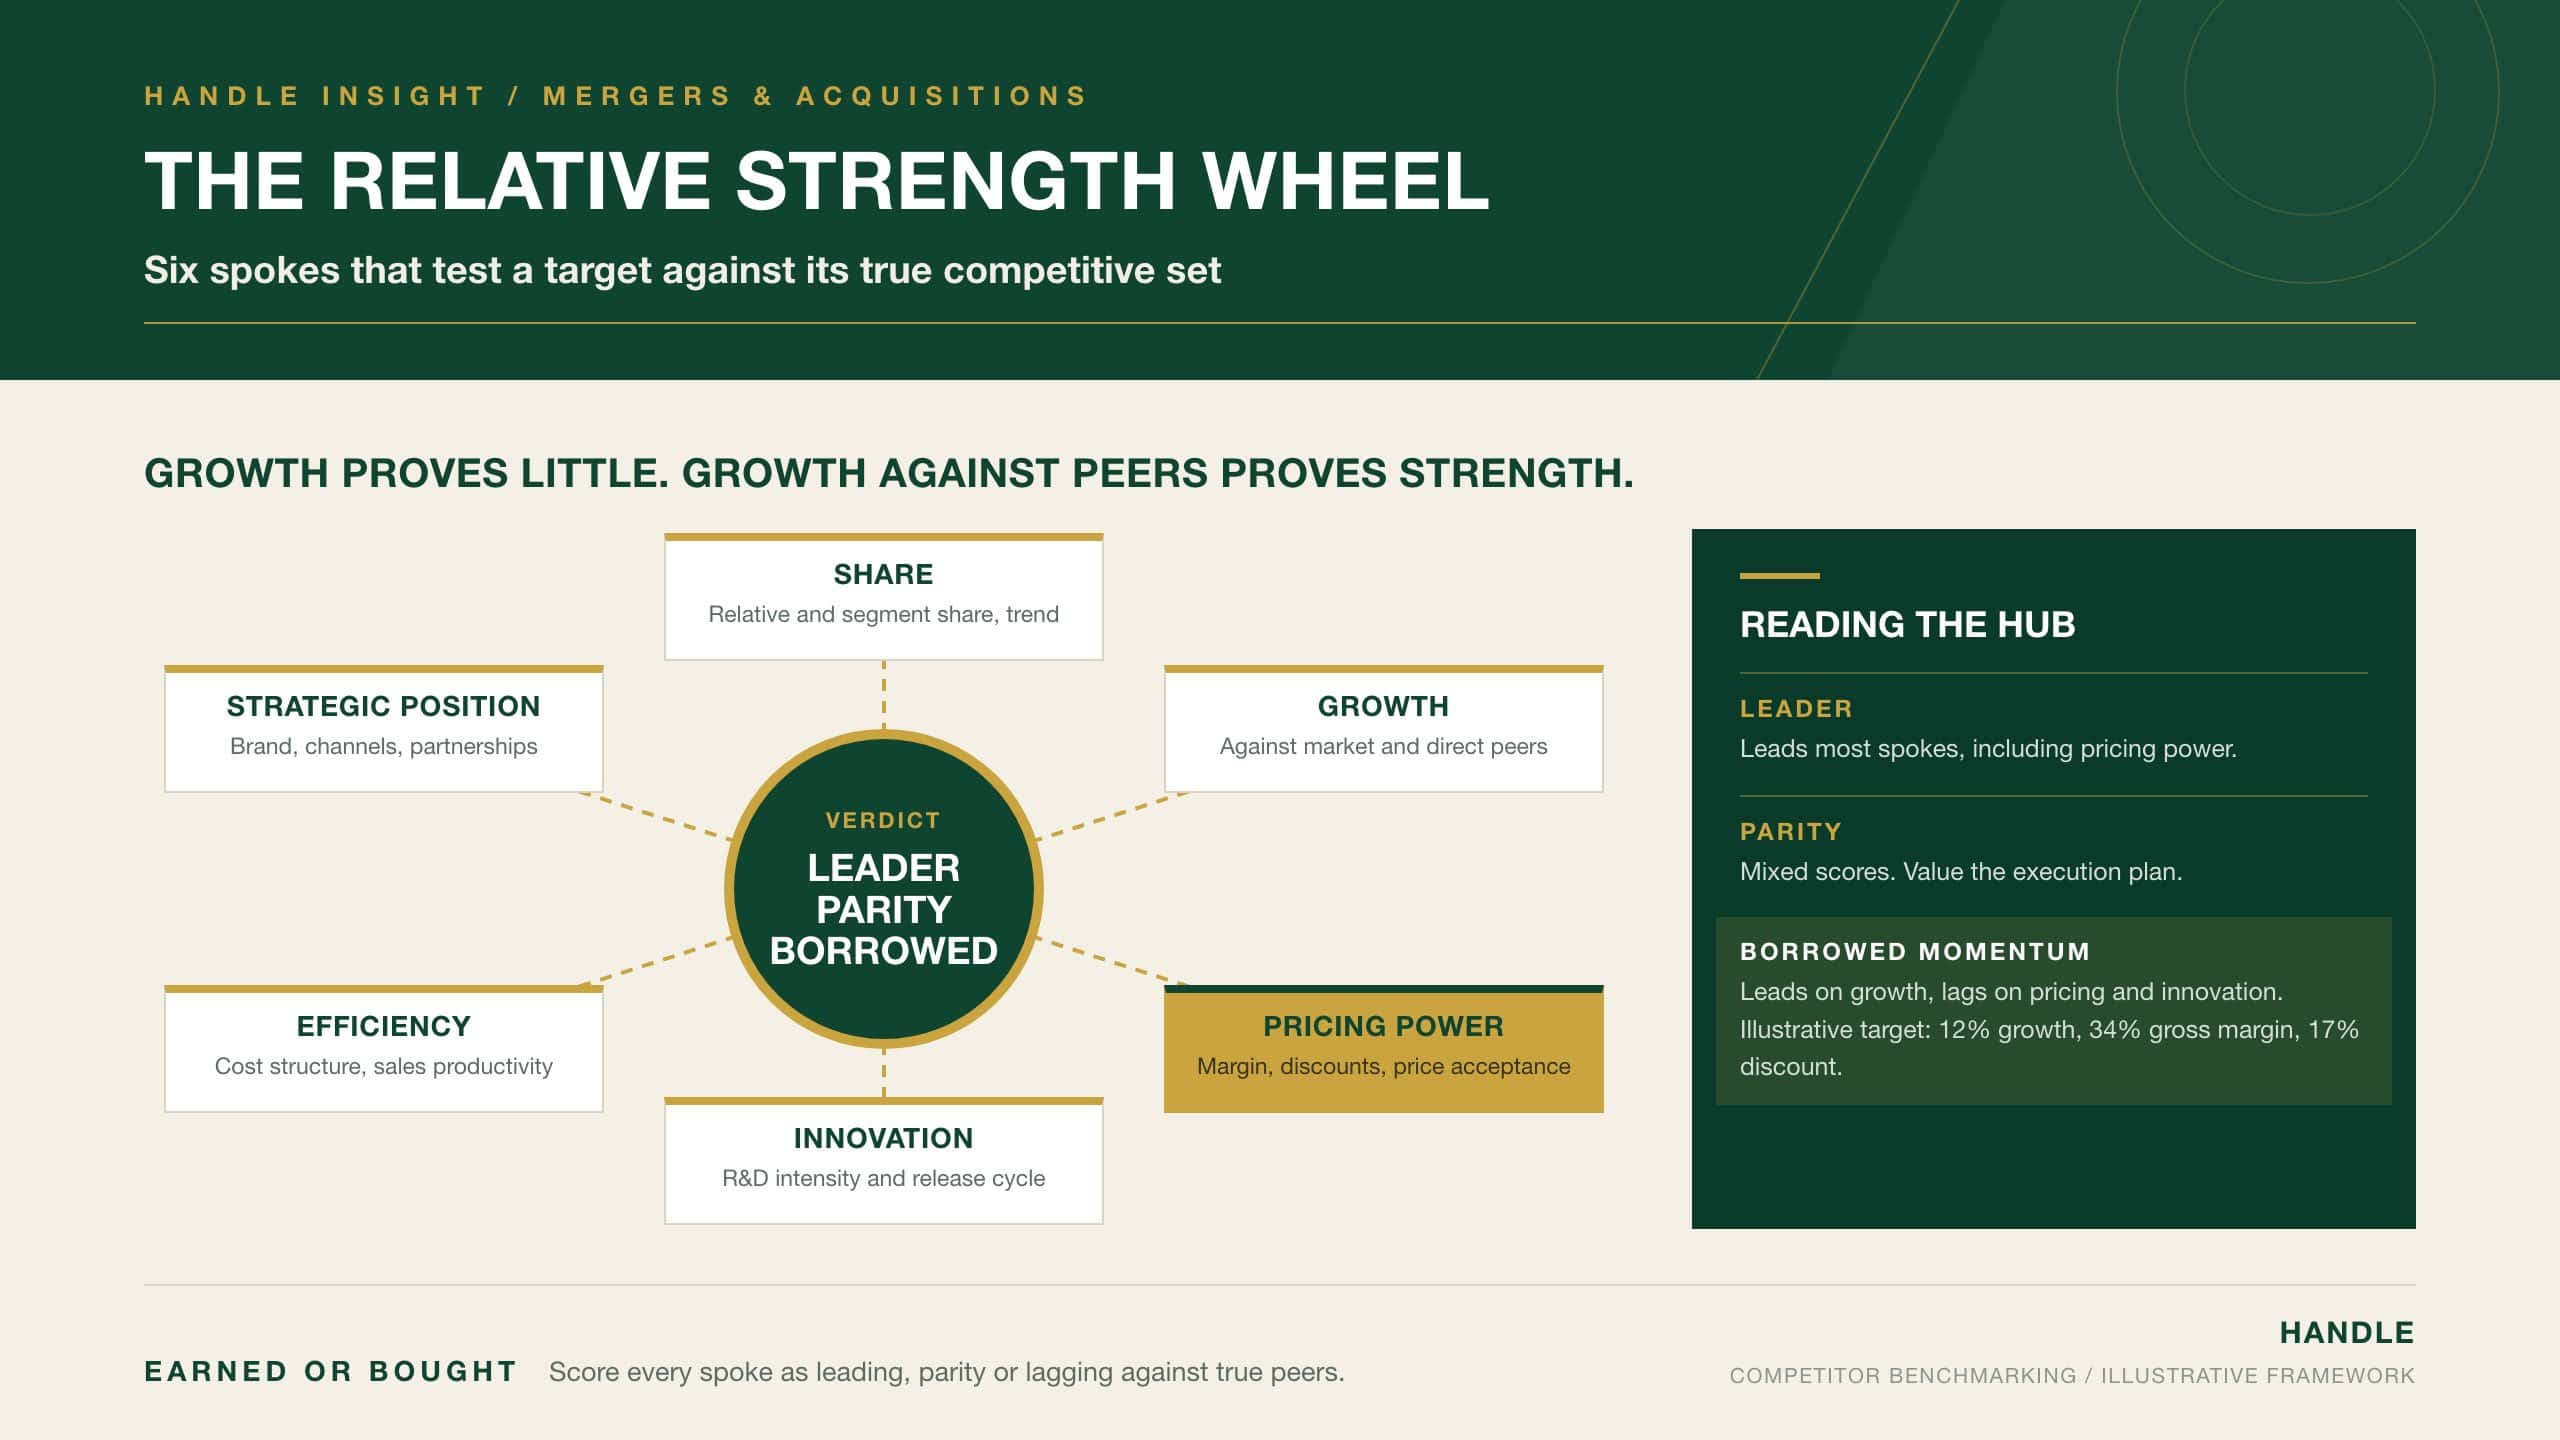
The Relative Strength Wheel organises benchmarking into six spokes around a single verdict. Each spoke compares the target with its true competitive set and scores it as leading, at parity or lagging.
| Spoke | Core Metric | Leading Signal | Lagging Signal |
|---|---|---|---|
| Share | Relative and segment share, with trend | Rising share in growing segments | Falling share despite revenue growth |
| Growth | Growth against market and direct peers | Above market and above peers | Below market or below peers with similar resources |
| Pricing power | Gross margin, discount levels, price acceptance | Premium sustained without discounting | Volume dependent on price concessions |
| Innovation | R&D intensity, release cycle, portfolio quality | Setting the product agenda | Following leaders with a lag |
| Efficiency | Cost structure, sales productivity, acquisition cost | Structural cost advantage | Higher cost to win and serve customers |
| Strategic position | Brand, distribution, partnerships, regulatory standing | Controls access to customers | Depends on others’ channels or platforms |
The hub converts the six scores into one of three verdicts. A target that leads on most spokes, including pricing power, is a market leader. A target with mixed scores is at parity and must be valued on its execution plan. A target that leads on growth but lags on pricing power and innovation, as in the worked example, is running on borrowed momentum: it is growing now on terms it cannot sustain. Pricing power is the spoke that most often decides the verdict, because it shows whether growth has been earned or bought.
Common Failures in Competitor Benchmarking
- Accepting management’s choice of peers, which often excludes the strongest competitors.
- Comparing growth with the market but not with direct peers, so that share loss to the leader goes unnoticed.
- Reading growth and margins separately rather than together, which hides discount-led growth.
- Ignoring indirect competitors and disruptors that will shape the market during the holding period.
- Presenting estimates for private competitors as precise figures without stating sources and ranges.
- Sharing competitively sensitive information outside clean team arrangements when the buyer is a competitor.
- Producing benchmarking findings that never reach the valuation model or the deal terms.
Conclusion
Competitor benchmarking in due diligence judges a target against the companies it actually competes with rather than against its own history or management’s chosen peers. It maps the true competitive set, then compares share, growth, pricing power, innovation, efficiency and strategic position, reading the metrics together so that bought growth is distinguished from earned growth. In the UAE, limited public data on private competitors calls for transparent estimates, and competition law requires care with sensitive information and consistency with any merger control analysis. The Relative Strength Wheel turns the comparison into a clear verdict: leader, parity or borrowed momentum. That verdict should move the price, shape the deal terms and set the first priorities after closing. If the target leads, capital can move with conviction. If it does not, the assumptions must change. Competitive reality decides the deal.


